Two weeks ago, we attended the 2025 Tax Reporting & Withholding Conference in Washington, D.C., where regulators, tax professionals, and industry leaders gathered to discuss the latest developments across digital assets, FATCA/CRS enforcement, treaty shifts, and evolving tax compliance obligations.
To support ongoing conversations and planning, we’ve compiled a summary highlighting key takeaways, from crypto reporting delays and Form 1099-DA rollout to new QI documentation risks, treaty suspensions, and CRS/AEOI enforcement trends.
If you weren’t able to attend, or just want a refresher, you can download the summary below. As always, we’re happy to connect further to explore how these changes may impact your organization and how our software solutions can help automate your tax compliance requirements.
Legislative Developments and Treaty Updates
Crypto Regulation Rollbacks and CARF
In 2025, the regulatory environment for crypto continues to evolve. Notably, the IRS and Treasury face setbacks in implementing the U.S. version of the OECD’s Crypto-Asset Reporting Framework (CARF). While regulations for digital asset brokers were finalized in July 2024 (focusing on U.S. sales to U.S. customers), the repeal of December 2024 DeFi regulations under the Congressional Review Act has disrupted broader implementation. The administration’s focus on supporting crypto growth suggests further crypto-specific regulations (like U.S. CARF) may stall.
U.S. participation remains speculative, though implementation of CARF in other countries begins Jan 1, 2026, with first exchanges in 2027.
America First Tax Measures
The America First Trade Policy is under IRS review, with potential consequences under IRC Section 891 if foreign jurisdictions impose discriminatory taxes on U.S. entities. This could double withholding rates under sections 871 and 881. Complementing this, the proposed Defending American Jobs and Investment Act (DAJI) introduces annual withholding rate increases (up to 50%) on payments to residents of countries with extraterritorial tax regimes.
Treaty Suspensions and New Agreements
Treaty developments include:
- Termination of the U.S.-Hungary treaty (effective Jan 1, 2024)
- Suspension of treaties with Russia (Aug 2024) and Belarus (Dec 2024)
- New treaty with Chile (effective Feb 2024) with reduced withholding rates
- Draft legislation for a “statutory treaty” with Taiwan offering treaty-like rates
Swiss IGA Transition
Switzerland will shift from a FATCA Model 2 to a Model 1 IGA effective Jan 1, 2027, simplifying reporting for Swiss FIs and eliminating the need for group requests. Withholding agents are not required to invalidate W-8 forms solely due to the change.

Tax Forms and Documentation Trends
Digital Asset Reporting
The IRS finalized Form 1099-DA and related digital asset regulations for custodial participants, effective January 1, 2025. However, regulations covering DeFi and non-custodial brokers were repealed, and U.S. CARF implementation is now uncertain.
Crypto ETFs, now structured as grantor trusts, introduce new tax questions. While hard forks and airdrops may create ordinary income, most ETFs disclaim entitlement to such events. Sales of crypto to pay ETF expenses may be reported under 1099-B or 1099-DA.
Form 1042-S Changes
Key updates for 2025:
- New income codes: 59 (Consent Fees), 60 (Loan Syndication), 61 (Settlement Payments)
- New Chapter 3 status codes: 40 (Partnership QDD), 41 (Certain exempt U.S. entities)
- New checkboxes for pool-to-recipient transitions
- Emphasis on use of Form 15397 for requesting payee statement extensions
Form 1042 Filing and Relief
IRS Notice 2024-26 extends paper filing relief:
- All withholding agents may paper file in 2024
- Non-U.S. withholding agents also exempt in 2025
Model 1 IGA TIN Relief Notice 2024-78 extends U.S. TIN relief for Model 1 FFIs through 2027, provided good-faith efforts (solicitation, DOB reporting, FTINs, address validation) are maintained. Jurisdictions must also demonstrate enforcement steps.

QI and FATCA/CRS Enforcement
QI and WP/WT Updates
- The new QI Agreement requires entities to consent to QI-EIN public disclosure
- Nominee reporting obligations clarified: generally, not applicable for foreign PTPs lacking a U.S. return requirement
- Substitute dividends: QIs must assume withholding responsibility unless upstream party is a QI/WP/USWA
FATCA/CRS and AEOI Compliance
- FATCA registration now requires Login.gov or ID.me authentication
- Increased enforcement activity across jurisdictions for CRS and FATCA compliance
- Common deficiencies: missing TINs, DOBs, nil filings, failure to report GIINs
- Jurisdictions are escalating desk audits and requiring detailed compliance documentation
It was our pleasure to be a part of this year’s Tax Reporting & Withholding Conference. If you missed our session on Technology & Testing Operational Controls, don’t worry, a recap is coming soon! Be sure to sign up to our mailing list so you don’t miss it.
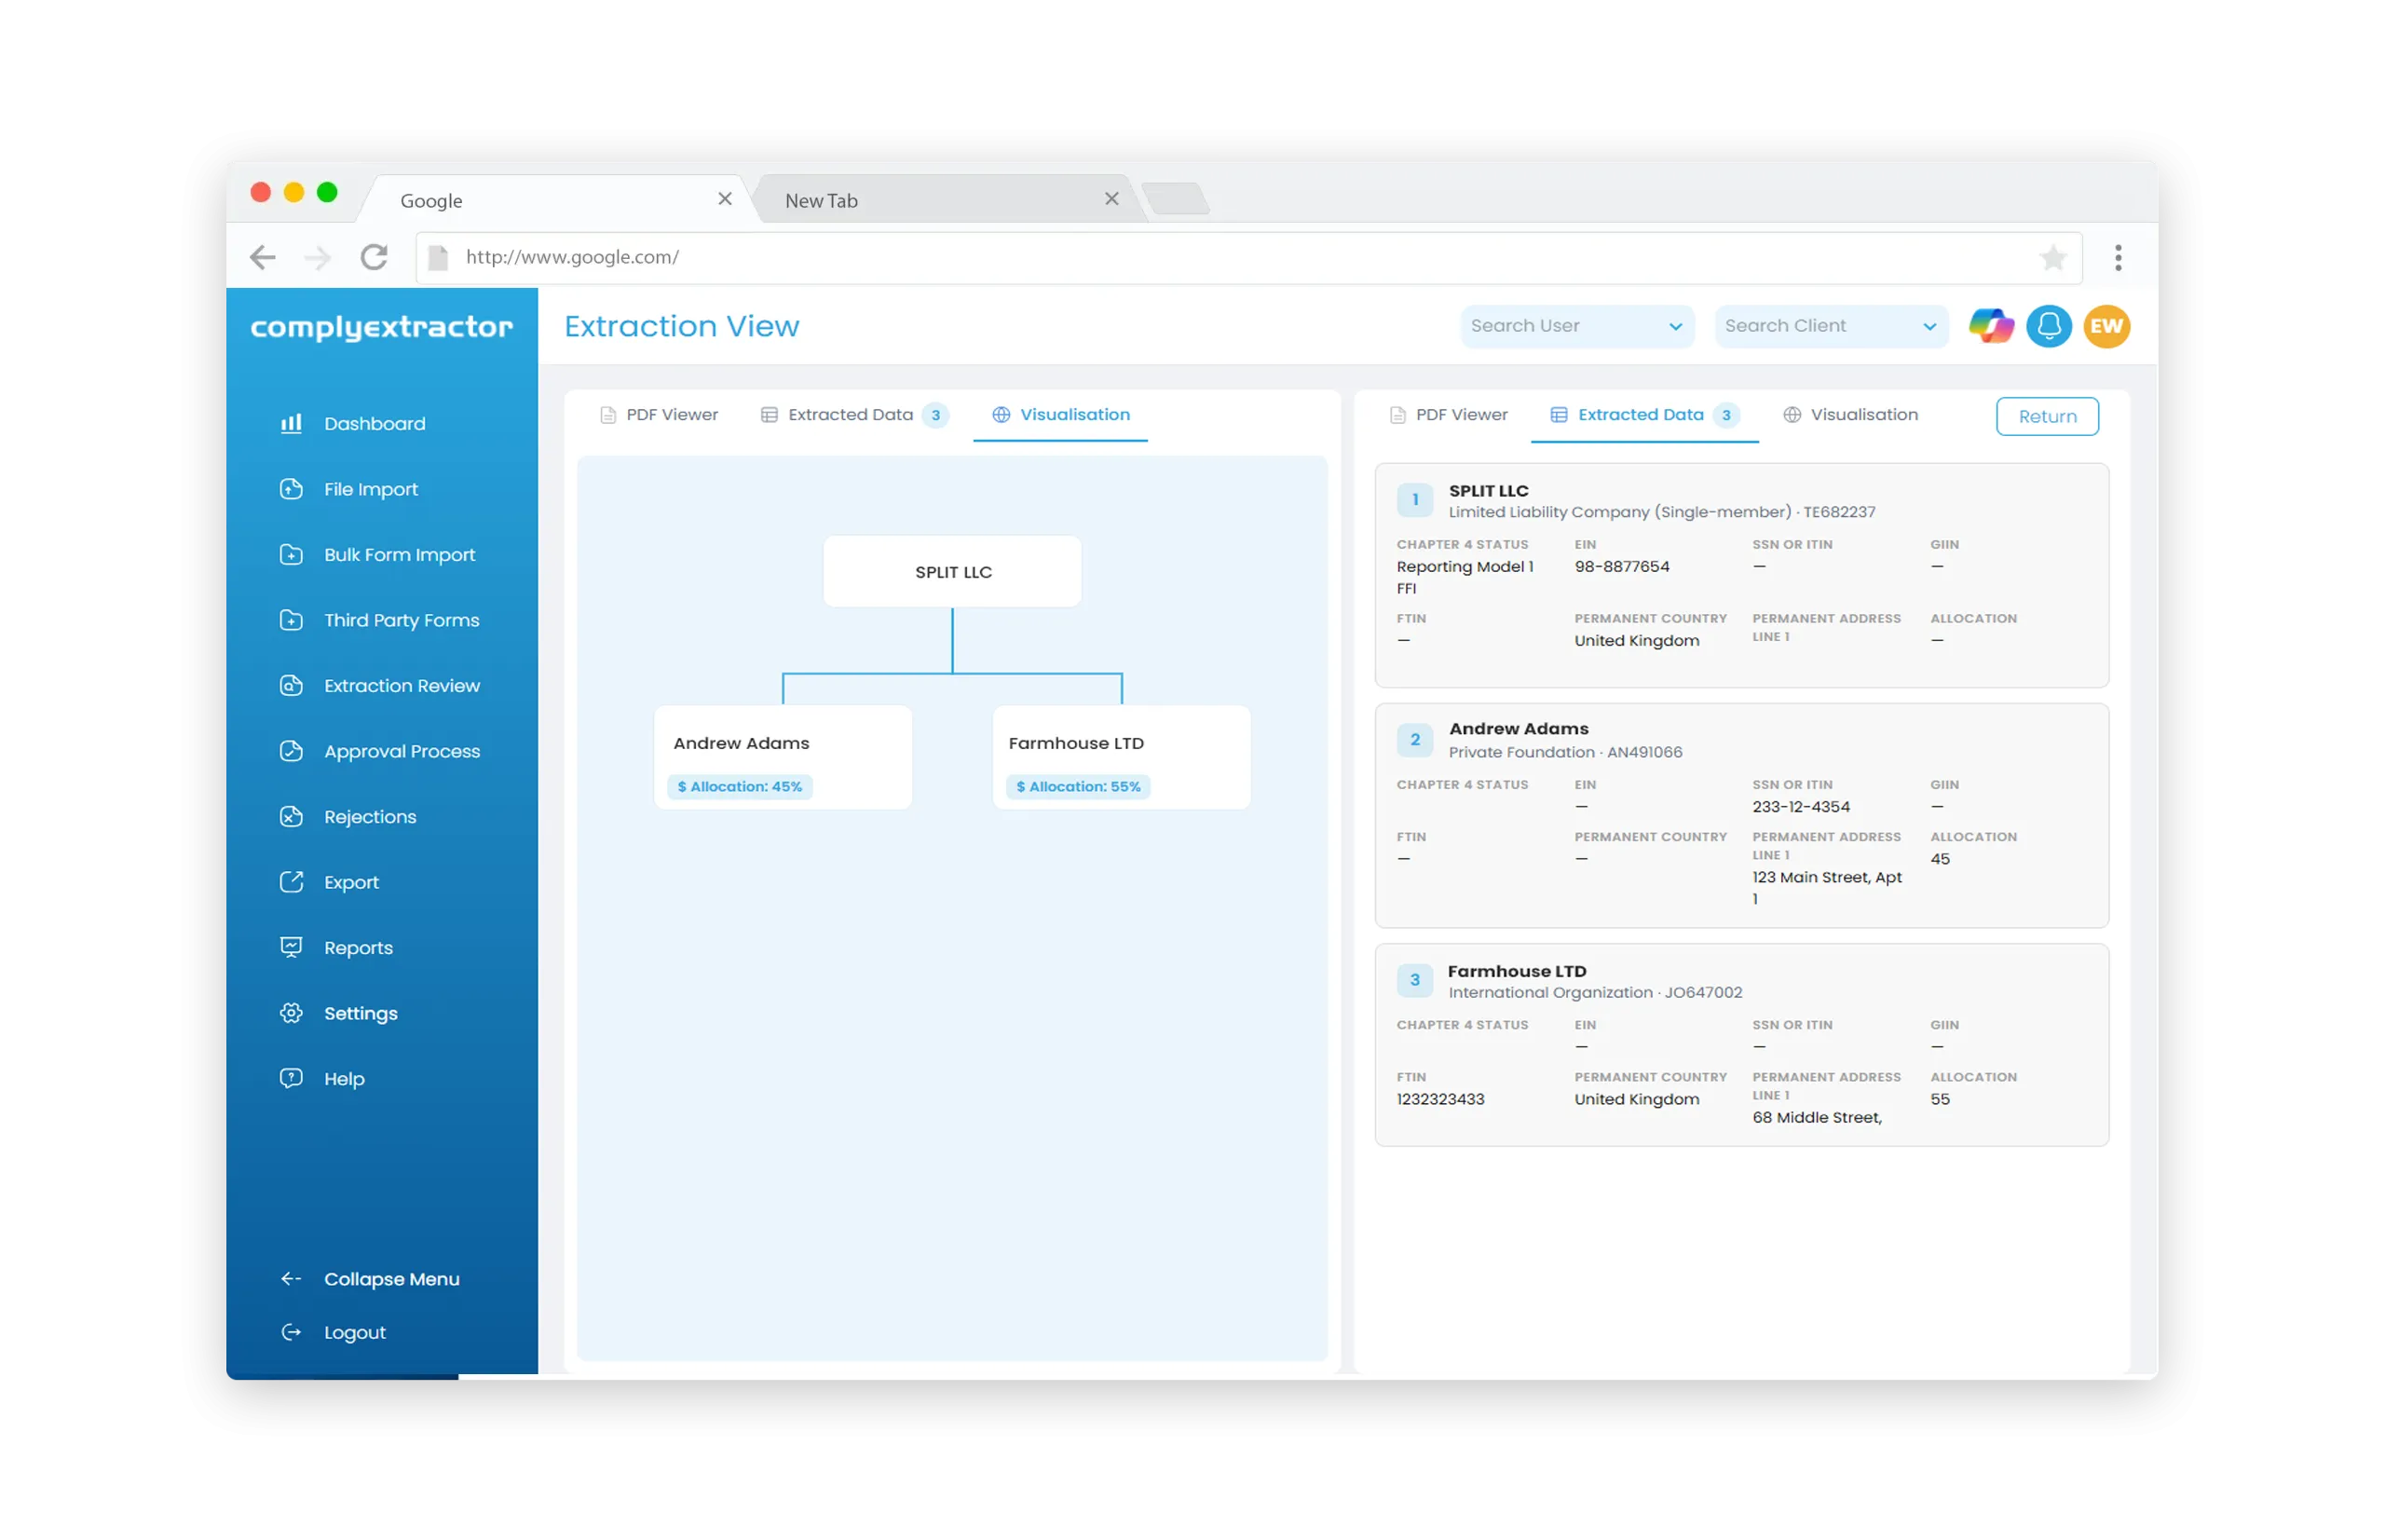
We’re also offering 5 free extractions with our AI-powered IRS Form and Withholding Statement Extractor, Comply Extractor. Experience firsthand how effortless tax form processing can be. Upload your IRS forms or a PDF pack with withholding statements, and let our AI handle the rest. From generating a fully compliant output structure to extracting key data from non-standardized paper forms, we turn your documentation chaos into organized clarity in minutes.