November 2024 | Issue 17
Comply Connect
Designed to keep you informed on the latest IRS news and updates in information reporting, while also providing valuable insights into what’s on the horizon for the upcoming month.
Coming Up in December
Discover the U.S. information reporting and withholding obligations and Comply announcements that you should keep an eye on in the coming month.
Key IRS Updates
Explore the Key updates provided by the IRS and other tax authorities from the last month you should be aware of.
FATCA & CRS Headlines
Take a look at our breakdown of the latest FATCA & CRS headlines to keep you up to date.
A message from our cEO:
With the Thanksgiving holiday approaching for our teams in the U.S., I want to extend my heartfelt gratitude to our clients, partners, and team for their unwavering trust and collaboration. Together, we’ve navigated regulatory complexities, introduced innovative solutions, and strengthened our position as leaders in tax compliance technology.
This year has been filled with milestones, from launching innovative solutions to enhancing partnerships and strengthening our shared commitment to simplifying tax compliance globally. These achievements are a testament to the dedication of our team and the trust of our clients and partners.
As we celebrate what we’ve accomplished together, we also look forward to the opportunities ahead, where we’ll continue to innovate and support you in meeting the challenges of a complex regulatory landscape. Thank you for being an integral part of our journey.

Coming up in December
Canada: Electronic Filing Services Unavailable
The Canada Revenue Agency (CRA) announced that electronic filing services will be temporarily unavailable for Registered Financial Institutions (RFIs) due to scheduled maintenance starting December 2, 2024. Services are expected to resume on January 13, 2025.
November 2024 Key Updates
Draft Form 1042-S Instructions
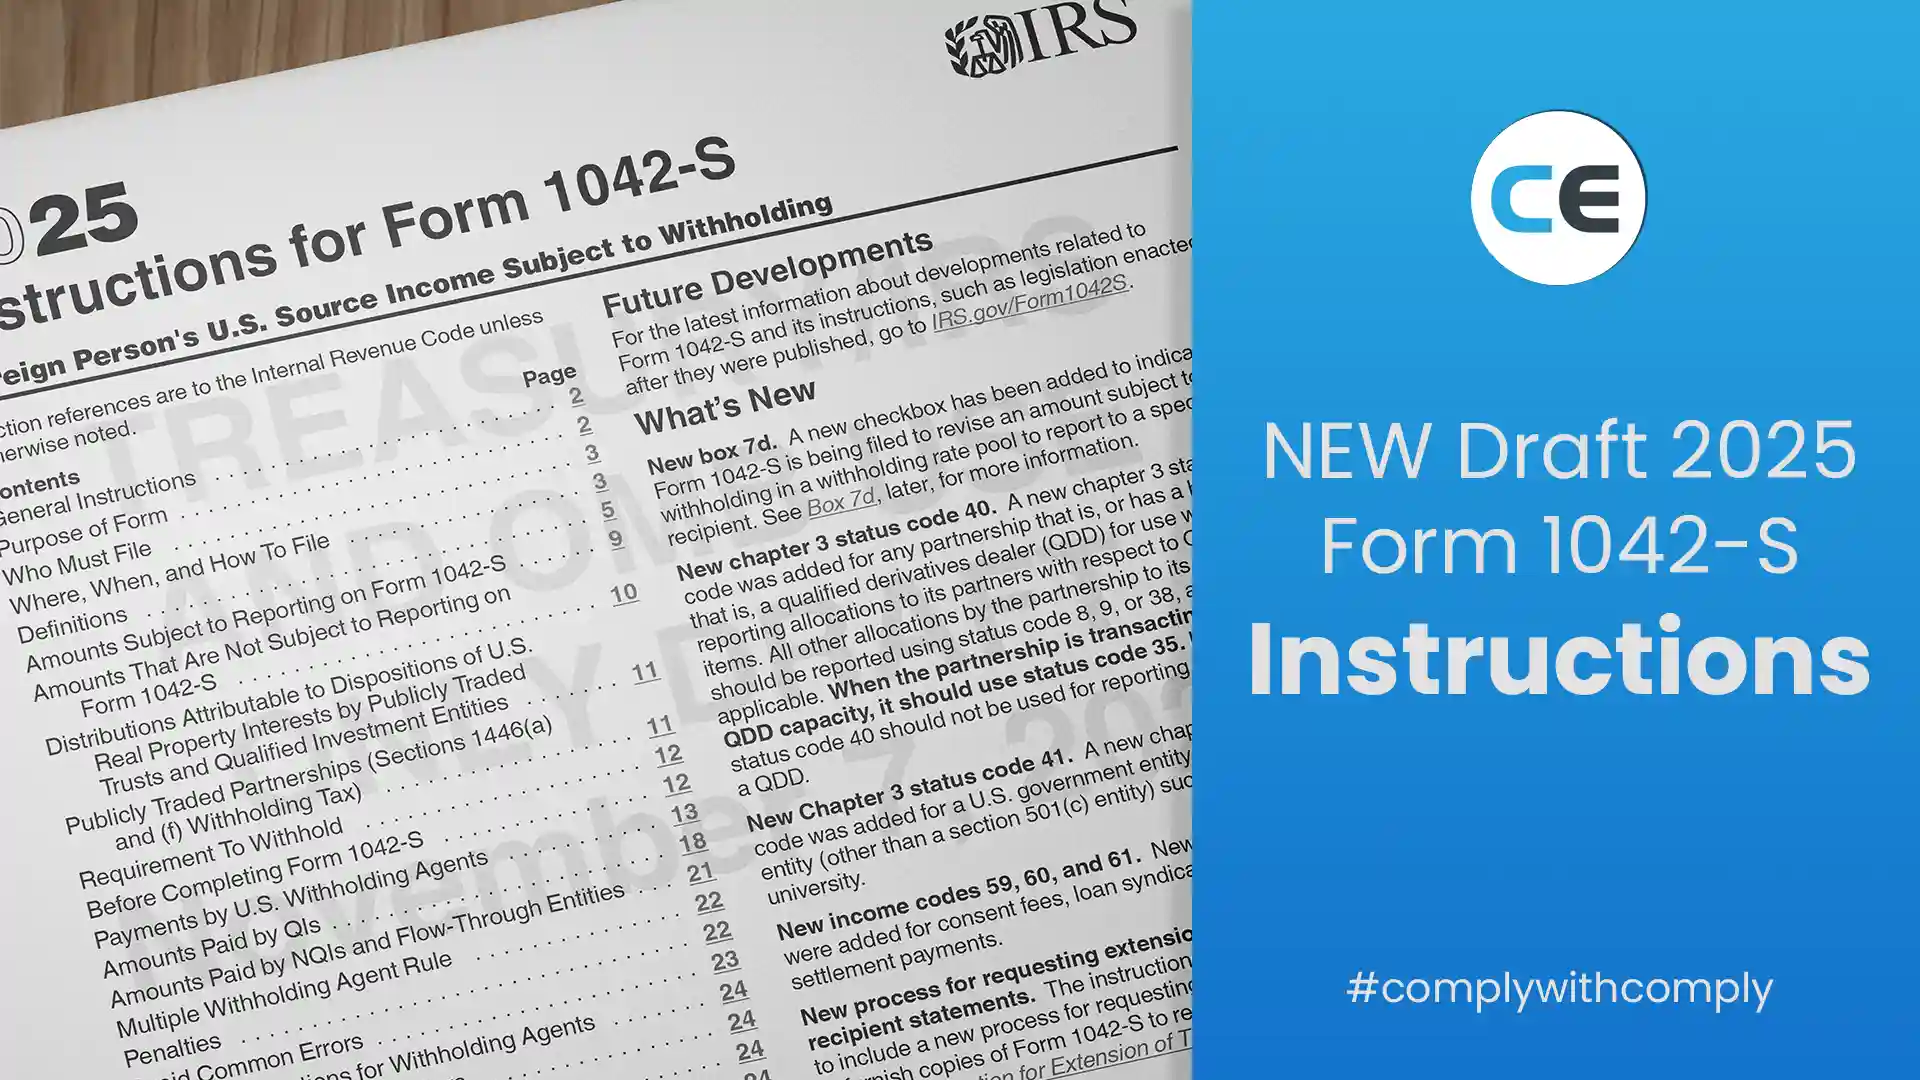
On November 7, 2024, the U.S. Internal Revenue Service (IRS) released draft instructions for the 2025 Form 1042-S, Foreign Person’s U.S. Source Income Subject to Withholding. This follows the earlier publication of the draft Form 1042-S on September 5, 2024. Please find a summary of the key updates below:
Extension Requests
The draft instructions outline the process for requesting a 30-day extension to furnish copies of Form 1042-S to recipients using Form 15397 (Application for Extension of Time to Furnish Recipient Statements). This request must be submitted by fax and received by the original due date for furnishing the recipient copies.
New Box 7d
A major addition to the 2025 Form 1042-S is box 7d, designed to simplify reporting for qualified intermediaries (QIs), withholding foreign partnerships (WPs), and withholding foreign trusts (WTs). Under specific conditions, these entities can report withholding amounts in aggregate pools rather than individually. However, if a recipient requests payee-specific reporting for amounts previously pooled, box 7d is used on the new Form 1042-S issued to the recipient and on the amended form that revises the withholding pool amounts.
When revisions occur after filing Form 1042 (Annual Withholding Tax Return for U.S. Source Income of Foreign Persons), it is necessary to amend Form 1042 to reflect the updated totals in lines 61a or 61b. This ensures accurate and consistent reporting.
New Income and Status Codes
The updated form introduces three new income codes:
- 59: Consent fees
- 60: Loan syndication fees
- 61: Settlement payments
These codes apply when payments don’t fit other specified income categories, excluding code 23 (other income).
Additionally, two new Chapter 3 status codes have been added:
- 40: Partnership QDD (Qualified Derivatives Dealer) for reporting partner allocations tied to QDD items.
- 41: U.S. government or tax-exempt entities other than section 501(c) entities, such as colleges or universities.
The instructions clarify that status code 40 should not be used to report payments to a QDD itself, which should use code 35.
Country Code Updates
The draft instructions now permit using “US” in box 13b (recipient’s country code) for income codes 27 (PTP distributions under IRC section 1446(a)) and 57 (amount realized under IRC section 1446(f)).
Future Changes
Looking ahead to the 2026 reporting year, the IRS intends to require a Chapter 3 exemption or reduced withholding tax rate code where tax withheld is less than 30%.
These updates aim to enhance the clarity and accuracy of Form 1042-S reporting.
Links to both the 2025 draft Form 1042-S and instructions can be found below:
- Draft Form 1042-S: https://www.irs.gov/pub/irs-dft/f1042s–dft.pdf
- Draft Form 1042-S Instructions: https://www.irs.gov/pub/irs-dft/i1042s–dft.pdf
Year-End Guide
Looking to dive deeper into these updates and understand their implications? Gain valuable insights from our subject matter experts by downloading our comprehensive Year-End Guide. This resource provides in-depth analysis and practical tips to help you navigate the changes effectively and ensure compliance with the latest IRS requirements.
Your Tax Compliance Guide to 2024 & 2025!
November 2024 FATCA and CRS Headlines
IRS: FATCA Scheduled Maintenance
The Internal Revenue Service (IRS) announced that the FATCA Registration System would undergo scheduled maintenance beginning November 25, 2024. During this period, the system will be unavailable. Financial institutions are advised to plan their reporting activities accordingly.
IRS: Issue Number 2024-30
On November 22, 2024, the IRS published Issue Number 2024-30, which includes the following updates:
- Manuel IDES confirmations sent to IDES users
- New IRS Public Key is available as of November 1st
- Historical IDES data available in IDES Web Dashboard
- Upcoming IDES multi-factor authentication implementation
- Reminder: IDES use for entities not required to obtain a GIIN
OECD: Multilateral Convention Update
On November 7, 2024, OECD published an announcement noting that Trinidad and Tobago signed the Multilateral Convention on Mutual Administrative Assistance in Tax Matters, bringing the total number of jurisdictions that participate in the Convention to 149.
Hong Kong: New Version of Encryption Tool
The Inland Revenue Department of Hong Kong published an update on the AEOI Portal noting that a new version of Encryption Tool has been released on November 11, 2024. This new version should be downloaded for encryption of data files.
Ireland: Revenue eBrief No. 267/24
On November 1, 2024, the Office of the Revenue Commissioners of Ireland published eBrief No. 267/24 informing customers that the following Tax and Duty Manuals (TDMs) have been updated:
- Part 38-03-22 Guidance Notes on the Implementation of Foreign Account Tax Compliance Act (FATCA) in Ireland
- Paragraph 43. Has been reworded for clarity.
- Part 38-03-24 Revenue Guide to Automatic Exchange of Information (AEOI) for Financial Account Holders
- Paragraph 12 has new wording adding to encourage account holders to provide their US TIN.
- Part 38-03-25 Filing Guidelines for Foreign Account Tax Compliance Act (FATCA)
- New wording added to paragraphs 7.5 and 7.6 to add clarity about the DOB and TIN elements of the schema.
- New wording added to paragraphs 7.5 and 7.6 to add clarity about the DOB and TIN elements of the schema.
Singapore: IRAS CRS TIN Guide
On November 21, 2024, the Inland Revenue Authority of Singapore (IRAS) published IRAS CRS TIN Guide (First Edition) to facilitate Reporting SGFIs in reviewing TIN information of their account holders. This guide contains the TIN and TIN equivalent information for the reportable jurisdictions that Reporting SGFIs must report on.

Never Miss Another Comply Connect!
Schedule a Demo
To learn more about our products and see them in action, schedule your personalized demo today. We tailor each demo to your business’s needs, allowing you to maximize your time with us.
What you can expect:
- A full end-to-end showcase of the Comply Ecosystem
- Consistent support for any queries and requirements before and after the session
- An open forum environment where you can ask any questions you desire
- A demonstration tailored to your business needs, so you can clearly see how it can benefit your operations