The Latest IRS, FATCA and CRS News for October 2025
- 11/03/25
- 10 Min Read Time

Coming up in November 2025:
Comply Exchange Year-End Reporting Guide
As 2025 winds down, it’s almost that time again, reporting season! Our upcoming Year-End Reporting Guide will help you navigate deadlines, avoid common errors, and stay fully compliant with the latest IRS requirements.
From key form updates to automation tips, this guide is your roadmap to a smoother reporting process. Stay tuned and make sure to sign up to our mailing list to download your free copy!
Finance & Accounting Technology Expo 2025
We’re excited to announce that we’ll be attending the Finance & Accounting Technology Expo (FATE) November 13th – 14th! With so many industry-leading speakers and insightful sessions, we’re looking forward to connecting and networking with some of the finest minds in finance and technology.
Finland: FATCA, CRS and DAC2 Information Session
The annual information session on FATCA, CRS and DAC2 obligations will be held on Wednesday, November 19, 2025. The session is intended for persons responsible for FATCA, CRS and DAC2 due diligence and reporting obligations. The event will be held in Finnish as a Teams meeting.
Germany: Deactivation of ELAN
The Federal Central Tax Office of Germany (BZSt) issued FATCA Newsletter 02/2025, providing the deactivation date for ELAN (ELMA and BOP) and date for the new interface, Digitial POStenter (‘DIP’).
ELMA will be deactivated on November 25, 2025. The new interface, DIP, will go-live in December 2025. During this transition period, XML upload functionality will not be possible. The implementation of this functionality will be announced in 2026. The individual data interface, BOP, will be available until March 2026, after which individual data reporting will be available through the BZSt online portal.
BZSt recommends making the necessary adjustments early and taking the transition phase into account accordingly.
IRS & Treasury Updates October 2025:
Fact Sheet FS‑2025‑08 — FAQs on Form 1099‑K Threshold
- On October 23, 2025, the IRS issued FAQs clarifying the reporting threshold for third-party settlement organizations (TPSOs) under the One Big Beautiful Bill Act (OBBBA).
- Key points include:
- The threshold for TPSOs to issue Form 1099-K returns to gross payments > $20,000 and more than 200 transactions in a calendar year. The Tax Books+1
- The lower threshold of $600 (from the American Rescue Plan Act) has been effectively unwound for federal reporting. The Tax Books
- Importantly, for payment-card transactions (credit/debit), no de minimis threshold applies even a single card payment triggers reporting.
IRS: Updated Form Releases
During October, the IRS released the following final and draft forms:
- FINAL Forms:
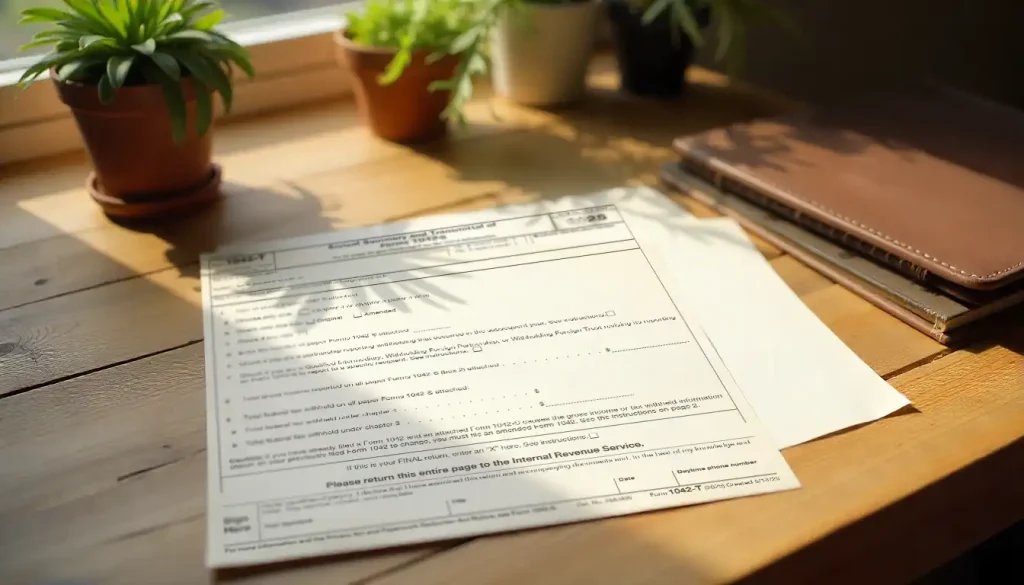
- 2025 Form 1042-T Annual Summary and Transmittal of Forms 1042-S
- 2025 Form 1042-T Annual Summary and Transmittal of Forms 1042-S
- DRAFT Forms:
- Form 1099-NEC (Rev. December 2026) Nonemployee Compensation
- Form 1099-MISC (Rev. December 2026) Miscellaneous Information
- Form 1099-K (Rev. December 2026) Payment Card and Third Party Network Transactions
- Form 1099-G (Rev. December 2026) Certain Government Payments
- Instructions for Form 1099-G (Rev. December 2026) Certain Government Payments
- 2026 Instructions for Form 1099-DA Digital Asset Proceeds From Broker Transactions
October 2025 FATCA, CRS and CARF Headlines:
Australia: Extension of Temporary U.S. TIN Relief
On October 27th, the Australian Taxation Office (‘ATO’) published an update regarding extension of temporary U.S. TIN relief for 2025, 2026, and 2027. To obtain this relief and avoid receiving a notice of non-compliance from the Internal Revenue Service (‘IRS’), Australian Financial Institutions should report certain pre-existing U.S. accounts with missing TINs as follows:
- Obtain and report the date of birth of each account holder that is an individual and controlling person whose U.S. TIN is not reported.
- Annually request from each account holder any missing U.S. TINs, providing relevent resources and instructions for obtaining a TIN.
- Annually search electronically searchable data maintained by the Reporting Model 1 FFI for any missing required U.S. TINs.
- Report an accurate TIN code for each account that is missing a required U.S. TIN.
- If the FFI’s electronically searchable account information contains a foreign TIN (FTIN), or functional equivalent, assigned to a taxpayer by its country of residence, report an FTIN for each specified U.S. person that is missing a required U.S. TIN. DO NOT report Australian TFNs. If the ‘country issued by’ element is ‘AU’, the TIN field must be ‘NA’. The IRS has provided a list of jurisdictions that do not issue foreign TINs or where laws restrict the disclosure of TINs.
- Use the AddressFix element to report the city and country of residence for each specified U.S. person with a missing U.S. TIN.
- Retain records of relevant policies, procedures, and compliance actions until 2031 for potential review by authorities.
Bahamas: FATCA and CRS Reporting Deadlines
The Bahamas Competent Authority posted key dates regarding FATCA, CRS, and CbC reporting. The AEOI portal opened on Wednesday, October 1, 2025, at 9am EST and will close on Tuesday, March 31, 2026, at 5pm EST. The portal will reopen in July 2026 for 2025 tax reporting.
Any financial institutions with FATCA, CRS, and CbC reporting obligations after the close of the portal in March should contact The Bahamas Competent Authority at helpdesk@taxreporting.finance.gov.bs or information@taxreporting.finance.gov.bs.
Barbados: Guidance Note OGC No. 12/2025
On October 21st, the Barbados Revenue Authority (‘the Authority’) issued Guidance Note OGC No. 12/2025, to provide clarity to Reporting Barbados Financial Institutions on the collection of tax identification numbers for new and pre-existing accounts. The notice represents an update to Guidance Note OGC No. 09/2023 issued by the Authority in November 2023.
British Virgin Islands: CRS 2.0 and CARF Notice
On October 23rd, the International Tax Authority (‘ITA’) of the British Virgin Islands posted a notice regarding CRS 2.0 and CARF.
BVI intends to introduce CRS 2.0 with effect from January 1, 2026. This means that by the end of 2026, Financial Institutions must collect the new information and ensure that it is submitted to the ITA by May 2027.
BVI has also committed to the implementation of the Crypto Asset Reporting Framework (‘CARF’). The commitment is for exchanges in 2028.
United Kingdom: Updates to International Exchange of Information Manual
The United Kingdom’s HM Revenue & Customs (‘HMRC’) updated the International Exchange of Information Manual (‘IEIM’) to include a new section, IEIM404510, Mandatory Registration.
All Reporting Financial Institutions (‘RFIs’) and Trustee-Documented Trusts (‘TDTs’) must register for HMRC’s AEOI service by the later of December 31, 2025, or January 31 following the calendar year in which the entity first falls within the definition of Reporting Financial Institution or Trustee-Documented Trust, for either or both CRS and FATCA purposes. For Reporting Financial Institutions that are already registered for AEOI, no further action is required.
Additional updates to this Mandatory Registration section include:
- When registering a TDT, the TDT should be shown as the reporting financial institution, not the trustee. The reporting trustee should be named as the contact.
- Registration is a single registration for AEOI covering both CRS and FATCA. Where an entity is in scope for either CRS or FATCA but not both, there is no requirement to notify HMRC which of the regimes the entity falls within.
- Registration is a one-off requirement. Once an entity is registered for the AEOI service, it will remain registered for subsequent years unless it deregisters from the AEOI service.
- If an entity registers and has no reportable accounts, there is no obligation to submit a nil return, though the entity may choose to do so.
- Entities that are brought within scope by CRS 2.0, such as Electronic Money Institutions, will meet the definition of Financial Institution starting January 1, 2026. The registration deadline for such entities is January 31, 2027.
- Financial Institutions that are taken out of scope by CRS 2.0, for example charities meeting the criteria to be Qualified Non-Profit Entities, may deregister from HMRC’s AEOI service from January 1, 2026. HMRC will accept that any such non-profit organization that has not registered with HMRC’s AEOI service because it has never had Reportable Accounts is not required to register by December 31, 2025.


Join Our Mailing List
Join Our Mailing List
A Message From Our CEO
It’s been a busy month for me and the entire Comply Exchange family! We had the pleasure of representing our sister company, Toknce, at this year’s London Blockchain Conference, where we gave attendees a sneak peek at what we’ve all been working so hard on. But we’re not slowing down, with more developments and events on the horizon, keep an eye out; you never know where we might pop up or what we are working on next!