Explore our tax withholding glossary for clear definitions of key terms used in U.S. withholding tax and compliance. Understand terminology relating to withholding agents, withholding rates, U.S.-source income, tax treaties, Forms W-8, Chapters 3 and 4, and the reporting of payments made to U.S. and foreign recipients.
Backup Withholding
A form of U.S. tax withholding that may apply to certain reportable payments when a payee fails to provide a correct TIN or meets other IRS-specified conditions.
FDAP Income
Fixed, Determinable, Annual or Periodical income, including items such as interest, dividends, rents and royalties. Certain U.S.-source FDAP income paid to foreign persons may be subject to withholding.
Treaty Rate
A reduced withholding tax rate that may apply to certain U.S.-source income when a foreign beneficial owner qualifies for benefits under an applicable U.S. income tax treaty.
Chapter 3
The section of the U.S. Internal Revenue Code that requires withholding agents to withhold tax, generally at 30%, on certain U.S.-source income paid to foreign persons, unless a reduced treaty rate or exemption applies.
Chapter 4
The section of the U.S. Internal Revenue Code containing FATCA withholding requirements, designed to encourage foreign financial institutions and certain foreign entities to report information about U.S. account holders and owners.
Chapter 61
The section of the U.S. Internal Revenue Code covering information reporting, including Form 1099 reporting and associated backup withholding.
Withholding Agent
Any person, U.S. or foreign, that has control, receipt or custody of U.S.-source income subject to withholding, and is responsible for withholding and reporting on it.
Qualified Intermediary (QI)
A foreign financial institution or other intermediary that has entered into a QI agreement with the IRS, allowing it to take on certain documentation, withholding and reporting responsibilities for its account holders.
Nonqualified Intermediary (NQI)
A foreign intermediary that is not a Qualified Intermediary and generally does not assume the same withholding and reporting responsibilities under a QI agreement with the IRS.
Beneficial Owner
The person who is required under U.S. tax principles to include a payment in gross income, as opposed to an agent, nominee or intermediary that receives the payment on their behalf.
NRA Withholding
U.S. tax withholding applicable to certain payments made to nonresident aliens and other foreign persons, generally involving U.S.-source income subject to Chapter 3 withholding rules.
Withholding Statement
Information provided by certain intermediaries or flow-through entities that allocates payments to underlying payees and supplies information needed to determine appropriate withholding and reporting.
Presumption Rules
Rules used by withholding agents to determine a payee's status or the appropriate withholding treatment when valid or sufficient tax documentation has not been provided.
Withholding Certificate
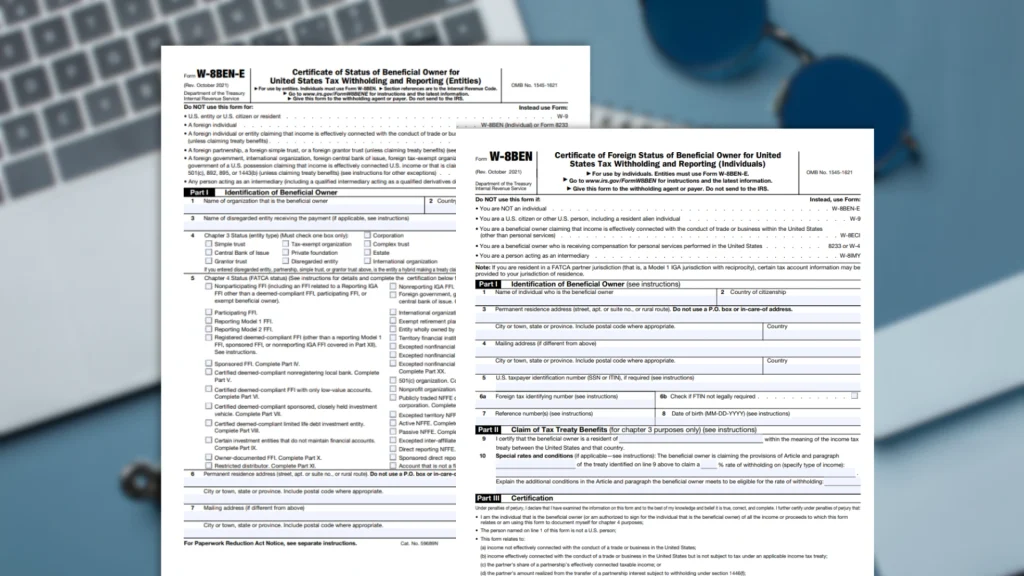
Documentation, including applicable Forms W-8, used to establish a payee's status and determine the appropriate withholding and reporting treatment for a payment.
Withholdable Payment
Generally, a payment of U.S.-source FDAP income that falls within the scope of Chapter 4 FATCA withholding, subject to applicable exceptions.